
Southeast Asia’s digital growth puts payment infrastructure in focus
Published on September 2, 2026
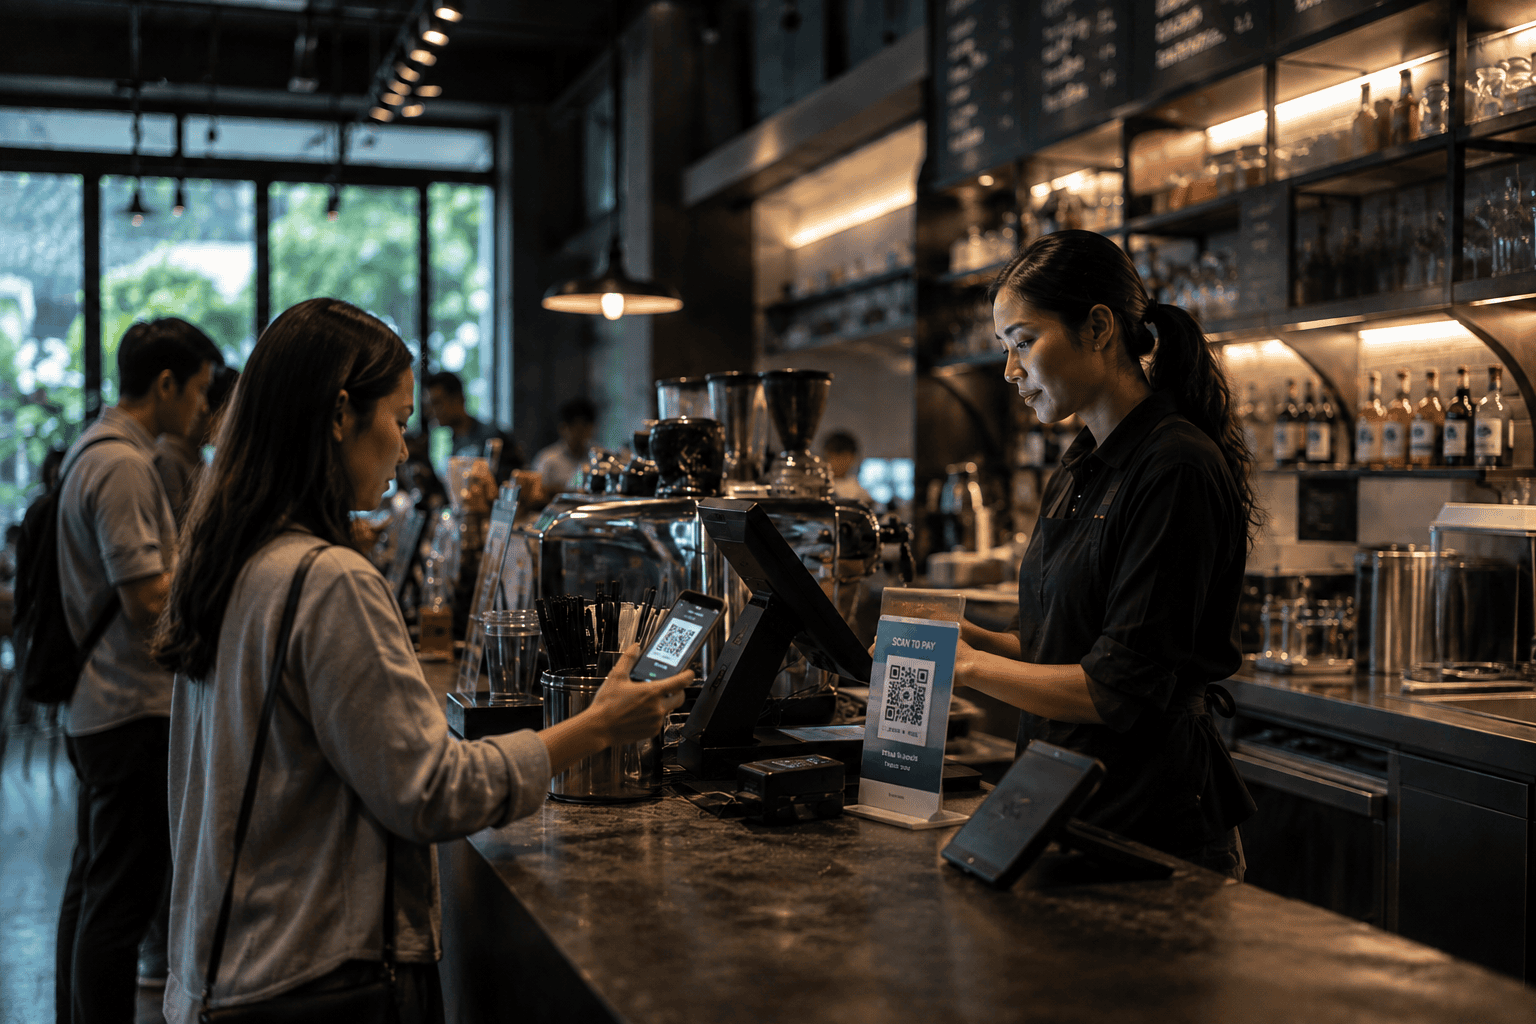
Southeast Asia has spent much of the past decade building the domestic rails for a digital economy. National payment networks such as Indonesia’s QRIS, Malaysia’s DuitNow, Thailand’s PromptPay and the Philippines’ QR Ph now operate at significant scale, connecting millions of consumers and merchants. But as commerce increasingly crosses borders, much of the infrastructure supporting it remains national, leaving businesses to navigate different payment systems, regulations, and currencies across the region.
The region’s digital economy surpassed US$300 billion in gross merchandise value (GMV) in 2025, with both GMV and revenue growing by approximately 15% year on year, according to Google, Temasek and Bain & Company’s e-Conomy SEA 2025. All 10 ASEAN markets now operate national QR systems, while eight have established cross-border QR interoperability. As businesses expand regionally, the ability to manage local payment methods, settlement, compliance, and reconciliation across multiple jurisdictions is becoming a more important part of how they operate.
Domestic rails reach meaningful scale
Digital payment adoption has accelerated across several of Southeast Asia’s largest economies. In Indonesia, QRIS reached 57 million users and 39.3 million merchants in the first half of 2025, more than 93% of which were micro, small and medium-sized enterprises. By the second quarter of 2026, BI-FAST processed 1.53 billion retail transactions, while QRIS transaction volumes grew 100.12% year on year.
Malaysia recorded 18.4 billion e-payment transactions in 2025, up 25% from the previous year, while DuitNow QR transaction volumes doubled to 3 billion in 2025. In Thailand, PromptPay processed more than 2.5 billion transactions in May 2026 alone. The scale and frequency of usage across these markets show how domestic payment networks have become part of the infrastructure of everyday commerce.
The Philippines has seen a similar acceleration in digital payments. According to the Bangko Sentral ng Pilipinas, digital payments accounted for nearly 65% of retail transaction volume in 2025, compared with 57% a year earlier, while QR Ph processed 2.47 billion transactions worth PHP 1.16 trillion.
The economics behind those transactions are equally important. The Philippine digital economy grew from US$26 billion in GMV in 2023 to US$36 billion in 2025, while average order values in video commerce are around US$4.50 to US$5.50. High transaction volumes and relatively small basket sizes put a premium on payment reliability.
As Ina Gatan, Head of GTM, Philippines at Xendit, recently observed, “A billion transactions a year at five dollars each is a market built on breadth. It also leaves no tolerance for failure.”
The implications extend beyond payments companies. For an e-commerce platform, the payment methods it supports can affect the customers it can serve. For an online travel company, an unsupported wallet can result in an abandoned booking. For a manufacturer operating across several ASEAN markets, settlement friction can become a working capital issue. Payments increasingly sit within the operating infrastructure of a business rather than functioning solely as the final step in a transaction.
A regional economy built on local systems
Southeast Asia’s payments landscape remains highly localised despite the growth of regional commerce. Each market has developed its own infrastructure, regulatory framework, banking relationships, settlement arrangements and consumer payment preferences. Businesses may increasingly serve customers across ASEAN, but the financial infrastructure underpinning those transactions still requires them to navigate individual markets.
Regional initiatives are beginning to bridge some of those differences. As of December 2025, 29 QR-payment and person-to-person instant-payment linkages had been established within ASEAN and with external partners. Nine ASEAN central banks have also joined the Regional Payment Connectivity initiative, which aims to make cross-border payments faster, cheaper and more transparent while supporting SME market access, trade and remittance flows.
Usage is developing alongside the infrastructure. According to the IMF’s 2026 analysis of ASEAN digital payments, cross-border QR payments in Thailand increased by more than 300% in 2024, while Malaysia recorded growth of 550%. Intra-ASEAN visitors accounted for 42% of total visitors in 2023, compared with 36% in 2019, adding to demand for payment systems that work across borders.
Connectivity, however, does not eliminate fragmentation. Current cross-border arrangements remain heavily bilateral, and adding another market can require additional work across payment operators, banks, compliance functions and regulators. For businesses expanding across Southeast Asia, that can mean navigating local acquiring, payment methods, settlement, licensing, fraud controls and reporting separately in each country.
The complexity creates demand for infrastructure that can connect local systems while managing the regulatory and operational requirements of individual markets. The challenge is not simply accepting a payment from another country, but making multiple domestic systems usable within a regional business.
Connecting Southeast Asia’s payment networks
Regional payment architecture is also becoming more interconnected. Project Nexus, backed by the Bank for International Settlements and participating central banks including Indonesia, Malaysia, the Philippines, Singapore and Thailand, is designed to connect domestic instant-payment systems through a standardised multilateral framework. Rather than requiring bespoke connections between every pair of markets, participants could connect once to a common platform. The BIS says the architecture could enable cross-border payments to reach recipients within 60 seconds in most cases.
The ASEAN Digital Economy Framework Agreement could provide a broader foundation for greater regional integration, covering areas including digital trade, cross-border e-commerce, digital payments, cybersecurity and digital identity. An ASEAN-commissioned study estimated that the region’s digital economy could approach US$1 trillion by 2030 through existing trends, with progressive DEFA rules potentially lifting the opportunity to US$2 trillion. These figures refer to the broader digital economy rather than payments alone, but indicate the scale of economic activity that regional financial infrastructure may ultimately need to support.
Greater interoperability will not remove the need for local infrastructure. Businesses operating across Southeast Asia will continue to require local payment-method coverage, compliance, foreign exchange, fraud management, settlement, payouts and reconciliation. The infrastructure challenge is therefore increasingly one of connecting and managing multiple systems while retaining the local capabilities each market requires.
Building the infrastructure for regional growth
ACV Capital-backed Xendit illustrates how this infrastructure is developing alongside Southeast Asia’s increasingly regional digital economy. The company operates across Indonesia, the Philippines, Malaysia, Thailand, Vietnam, Singapore and Hong Kong. Its regional expansion has included entering Thailand in 2024, acquiring Malaysia-based Payex in 2025, and integrating Philippine payment platform Dragonpay.
That footprint reflects the local complexity accompanying regional expansion. A merchant moving from one Southeast Asian market into another encounters different payment methods, banking systems, and regulatory requirements. Infrastructure that connects businesses to local payment rails can reduce the need to rebuild payment operations market by market while retaining the capabilities required in each jurisdiction.
Xendit provides payment infrastructure across Southeast Asia, including cross-border collections and payouts for businesses expanding within the region. Its development reflects a broader shift in the market from building individual payment methods toward connecting the systems businesses need to operate across multiple markets.
As Gatan noted, “My view is that the next 10 years will favour companies that can scale across multiple ASEAN markets, work with regulation rather than around it, localise, and earn trust.”
Cross-border payment links are expanding, but the operating requirements remain largely market-specific. Routing, settlement, compliance, risk management and reconciliation still need to be managed across individual markets.
Infrastructure behind Southeast Asia’s digital growth
Rising transaction volumes are only part of the case for payment infrastructure. Domestic digital adoption is already compounding from a substantial base, while regional connectivity is bringing previously separate payment systems closer together. The ability to reduce the complexity of operating across those systems will become more important as businesses and consumers transact across borders more frequently.
There are also execution challenges. Greater interoperability can place pressure on payment pricing, regulatory frameworks will continue to differ across markets, and faster cross-border payments increase the importance of fraud prevention, anti-money laundering controls, data protection, and operational resilience. These considerations are integral to the economics of regional payment infrastructure and help distinguish basic connectivity from infrastructure capable of supporting businesses at scale.
Xendit’s development reflects the changing infrastructure requirements of Southeast Asia’s digital economy. As commerce becomes more regional, the systems that allow businesses to collect, move and manage money across markets are becoming increasingly important. Southeast Asia has built sophisticated domestic payment rails; connecting and managing them across markets is becoming an important part of the region’s digital growth.